Few situations are more frustrating than being hit by a negligent driver, only to have your insurer inform you that you must pay an upfront policy excess before repairs can begin. Whether that figure sits at £250, £500, or higher, paying out of your own pocket for an incident someone else caused feels fundamentally unfair.
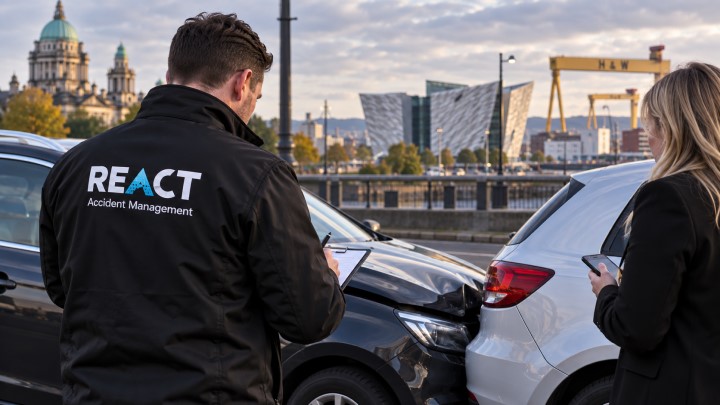
In Northern Ireland, your obligation to pay an excess comes down to a clear distinction: the specific legal mechanism you use to process your claim.
Understanding how claims operate under Northern Ireland common law can save you substantial out-of-pocket expenses while preserving your future insurance premiums.
Understanding Policy Excess
An insurance excess is a contractual clause within your personal motor policy. It represents the agreed amount you must contribute toward any claim processed through your own comprehensive cover.
When you instruct your own insurer to handle repairs, their claims department operates strictly within the terms of that contract. Because their priority is indemnifying the vehicle under your policy terms, they apply the excess automatically—even when the other driver is clearly at fault.
The Two Post-Accident Routes
The Standard Insurer Route:
[Collision Occurs] ➔ [Claim via Own Policy] ➔ [Pay Excess to Bodyshop] ➔ [Wait Months for Insurer to Recover Funds]

The React Accident Management Route:
[Collision Occurs] ➔ [Contact React] ➔ [Zero Excess Charged] ➔ [Costs Billed Directly to At-Fault Insurer]
Route 1: The Traditional Comprehensive Insurance Route
-
Mandatory Excess Payment: Your insurer typically instructs their approved repairer to collect your compulsory and voluntary excess before handing your car back.
-
The Recovery Period: Your insurer will attempt to recover that excess from the negligent third party’s insurer. While straightforward liability admissions might resolve in 8 to 12 weeks, disputes or delays from the third party can leave you waiting 6 to 12 months for a refund.
-
The “Open Claim” Impact: While your insurer pursues the third party, the claim remains open on your file. If your policy renews during this window, your No Claims Bonus (NCB) may be temporarily scaled back, leading to an artificially inflated renewal premium.
Route 2: Independent Accident Management (Credit Repair)
Under the law of tort in Northern Ireland, a negligent motorist is liable for all reasonable financial losses resulting from their actions.
When you work with an independent specialist like React Accident Management, you do not claim under your own insurance policy. Instead, you exercise your common-law right to recover losses directly from the at-fault driver’s insurance:
-
Zero Out-of-Pocket Expense: You never pay a single penny of policy excess to the repairer.
-
Direct Insurer Billing: The repairer bills the negligent party’s insurer directly through an approved credit repair framework.
-
Protected No Claims Bonus: Because no claim is made against your comprehensive policy, your earned discount remains secure and intact.
What About Uninsured Losses?
Your policy excess is classed legally as an uninsured loss—a direct financial detriment caused by the third party. Other common uninsured losses include:
-
Travel fares and fuel expenses incurred while without a vehicle.
-
Damaged personal property inside the car (e.g., child car seats, mobile devices, tools).
-
Loss of earnings caused by medical appointments, recovery, or transport issues.
Under the conventional insurance route, recovering these sums requires you to pursue the third party yourself or pay extra for optional “Motor Legal Protection.” React handles uninsured loss recovery as an integral part of our standard claims management service.
Practical Steps Following a Non-Fault Crash in NI
To make sure your claim proceeds smoothly without excess deductions:
-
Exchange Complete Details: Record the other driver’s full name, phone number, address, vehicle registration, and insurance provider.
-
Document the Scene: Photograph vehicle positions before they are moved, capture close-ups of all damage, skid marks, road layout, and local signage.
-
Identify Independent Witnesses: Obtain names and contact numbers of nearby motorists or pedestrians who witnessed the collision.
-
Call React Before Contacting Your Insurer: Reach our 24/7 team on 028 9002 1600. We review liability immediately and structure your claim so you avoid paying an unnecessary excess.
Frequently Asked Questions
Can my insurer force me to pay an excess if the other driver admitted fault at the scene?
Yes, if you choose to process the repairs through your own policy. A roadside admission is not legally binding on an insurance company. Until the third-party insurer formally accepts liability in writing, your own insurer enforces standard contract terms, including the excess. Using React bypasses this mechanism entirely.
Do I still need to notify my own insurance company?
Yes. Most UK and Northern Ireland motor policies require policyholders to report any road traffic incident within a reasonable timeframe for notification purposes. When contacting them, simply state: “I am reporting this collision for information purposes only; the non-fault claim is being handled independently by an accident management firm.”
Will an accident management claim affect my future insurance quotes?
You must disclose all motoring incidents when applying for insurance coverage. However, when zero outlay is made by your insurer and full liability is recovered from the third party, your No Claims Bonus percentage remains untouched.